Charleston SC Flood Zones: A Buyer and Seller Guide
If you're buying or selling a home in the Lowcountry, the flood zone question comes up fast. Charleston SC flood zones shape what you pay for insurance, what your lender requires, and how a home has to be built. The good news: you can look up any address in a few minutes, for free.
Here is how I walk my clients through it.
Start with the address. Then use one of these free tools:
The current FEMA flood maps for Charleston County took effect on January 29, 2021. That includes the City of Charleston, Mount Pleasant, Sullivan's Island, and Isle of Palms. Maps get updated, so check again before you buy.
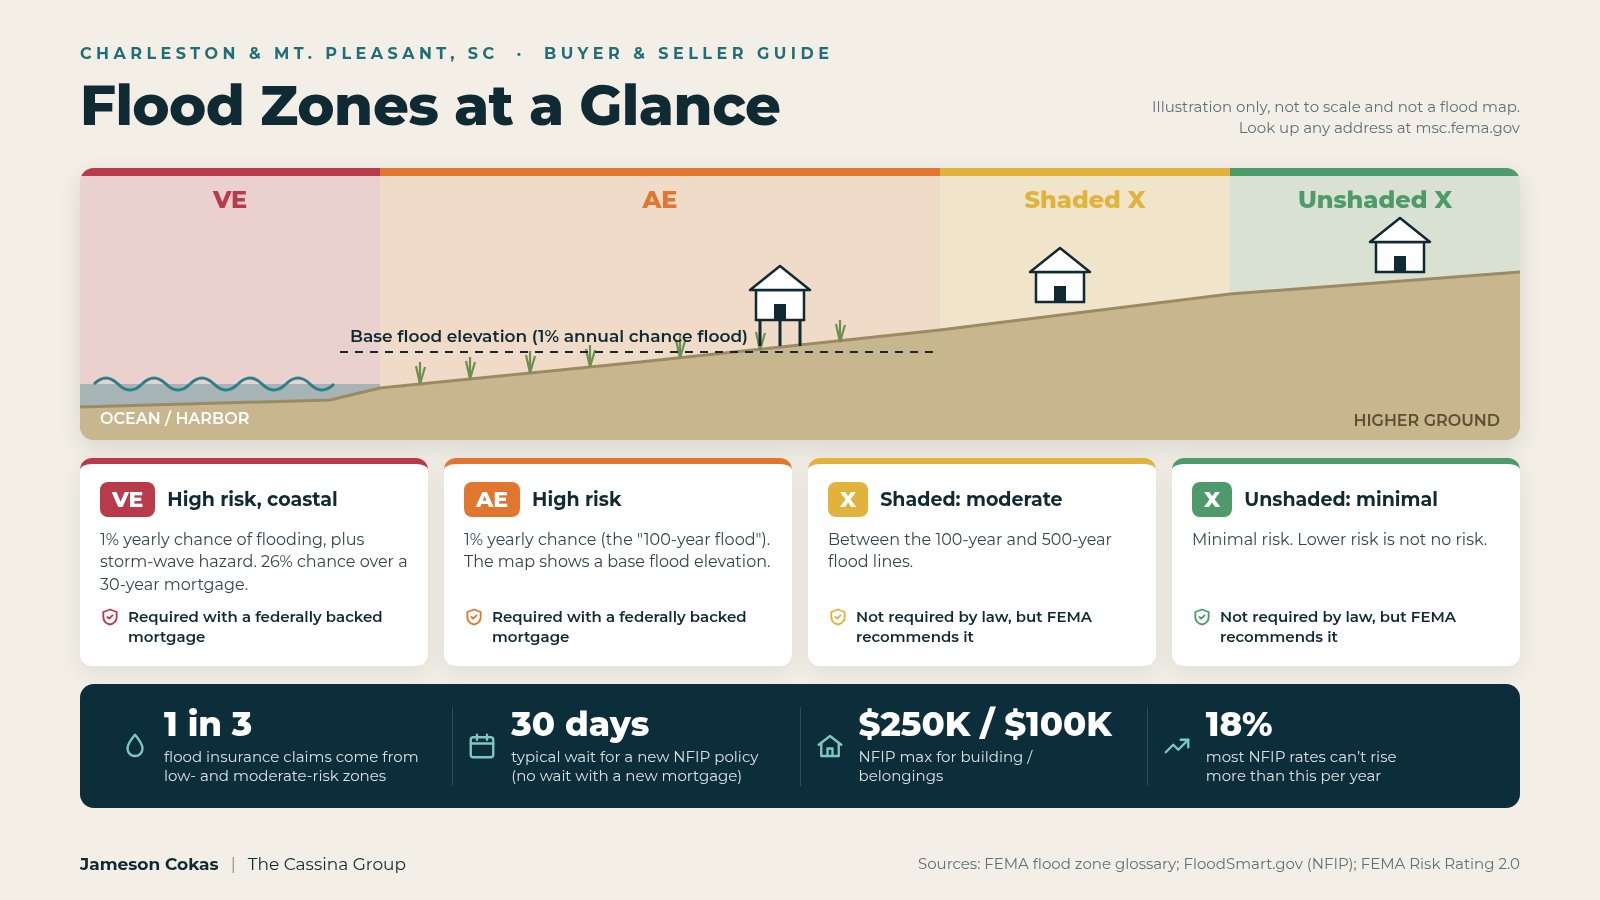
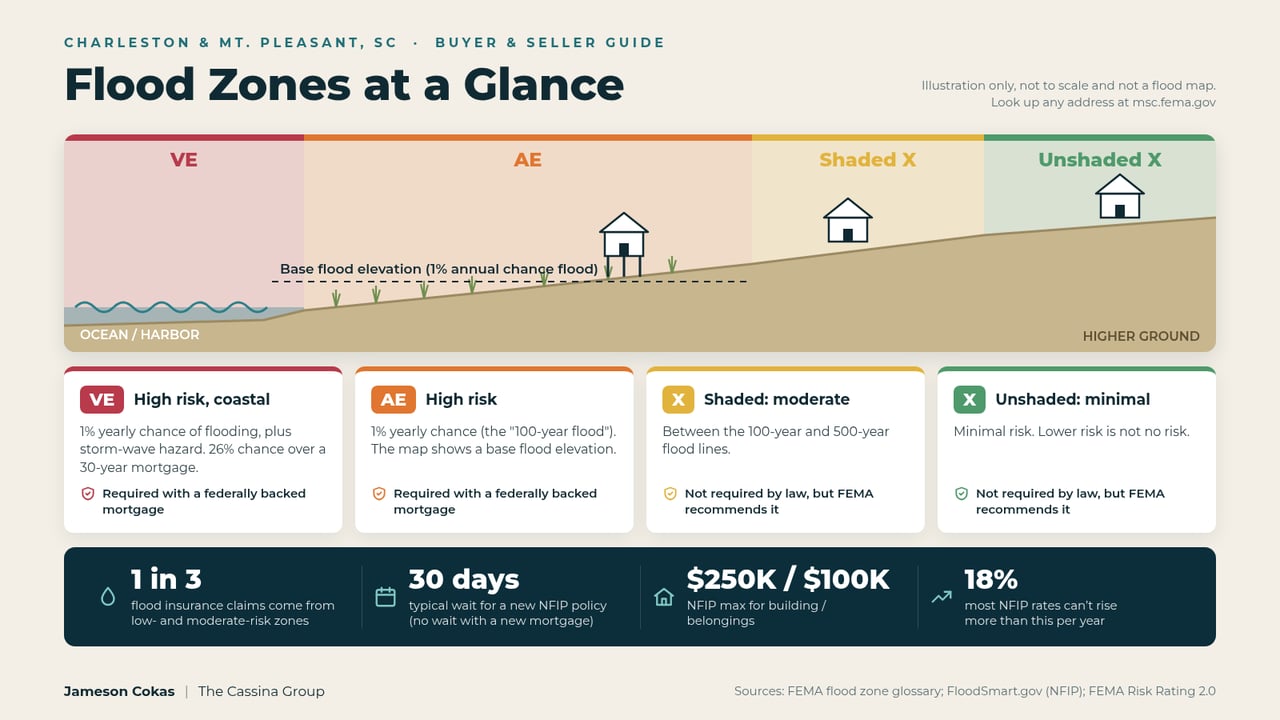
Here are the zones you'll see most around here:
Mount Pleasant's maps also show a Coastal A Zone, which the Town regulates like a VE zone.
Lower risk is not no risk. FEMA says about 1 in 3 flood insurance claims come from low- and moderate-risk zones.
If the home is in a high-risk zone (A or V) and you have a federally backed mortgage, yes. Flood insurance is required as a condition of the loan.
If the home is in Zone X, or you're paying cash, it's your call. FEMA still strongly recommends it. And most standard homeowners policies do not cover flood damage.
Have an address in mind? Send it my way. I'll help you look up the flood zone before you write an offer.
FEMA's National Flood Insurance Program (NFIP) prices policies with a method called Risk Rating 2.0. It started for new policies on October 1, 2021, and was fully in place by April 1, 2023.
Your rate is based on the home itself, not just the zone. FEMA looks at:
A few more basics:
An elevation certificate shows how high a building sits compared to how high floodwaters are expected to get. In high-risk zones you may need one, and it can help you qualify for a lower premium.
Ask the seller first. If they don't have one, check with the local floodplain office. The City of Charleston posts the certificates it has on file in MAPNET. Mount Pleasant keeps them on file for homes built in its high-risk zones, and a copy costs $20. If none exists, a licensed land surveyor or engineer can complete a new one.
A new NFIP policy usually starts 30 days after you buy it. The big exception for buyers: there is no wait when you buy flood insurance as part of getting a new mortgage.
If you already own, don't wait for a storm in the forecast. The Atlantic hurricane season runs June 1 to November 30, and a policy bought today wouldn't start for about a month.
Looking near the beach? My Isle of Palms home buyer's roadmap covers island-specific steps. Shopping on the peninsula? Start with my downtown Charleston home buyer's guide.
South Carolina's property disclosure form asks sellers about flood zones and flood risk, current flood insurance, flood claims, flood repairs, and federal flood aid during their ownership. Gather your records early:
A tip many sellers miss: if your NFIP policy has a discount, FEMA says you can pass it to your buyer by assigning the policy at the sale.
Zone X is on FEMA's map, but it sits outside the high-risk area. Flood insurance isn't required by law there, but FEMA still recommends it.
AE is a high-risk zone with a 1% chance of flooding each year. With a federally backed mortgage, flood insurance is required.
It depends on the home. FEMA says each premium is unique to the property. The best way to know is a quote for the exact address from a licensed insurance agent.
Yes. FEMA updates maps over time, and an owner can request a Letter of Map Amendment or Letter of Map Revision. Learn more on FEMA's FloodSmart flood zone page.
Flood zones can feel confusing. They don't have to be. Send me any address in Charleston, Mt. Pleasant, or the islands. I'll help you look up its flood zone, check for an elevation certificate, and put together a short list of questions for your insurance agent.
This post is general information, not insurance or legal advice. For coverage and pricing, talk with a licensed insurance agent.
Call or text me at (443) 864-2332, or email [email protected].
Talk soon,
Jameson
The Charleston County 4% legal residence rate can lower the property tax on the home you live in. But it isn't automatic. Here's who qualifies, what to send, and when … Read more
Market Update
Market Update
October 2026 CTAR numbers for Upper and Lower Mount Pleasant, what moves a home's price, and how a real pricing analysis works.
Market Update
A plain-English guide for buyers and sellers: the deed recording fee, attorney closings, tax prorations and the costs on your Closing Disclosure.
Market Update
2026 home prices, days on market, commutes and county lines for 11 areas around Charleston, side by side.
Three local governments, a big county park, flood zones that vary by street, and what homes sold for this fall.
Market Update
Winter vs. spring by the numbers, and how to get your home ready this season.
Flood and evacuation zones, the 4% property tax rate, and your first 45 days as a South Carolina resident.
Experience the white-glove service you deserve! With a background in sports and entertainment real estate, he exceeds expectations, delivers quality advice, and ensures your best interests are always prioritized. Choose excellence for your real estate journey.